-
Our solutions
- Our clients
With 300 clients and 60,000 users spread across 60 countries around the world, Murex has a truly international client base of capital markets participants.
view all case studies- Who we are
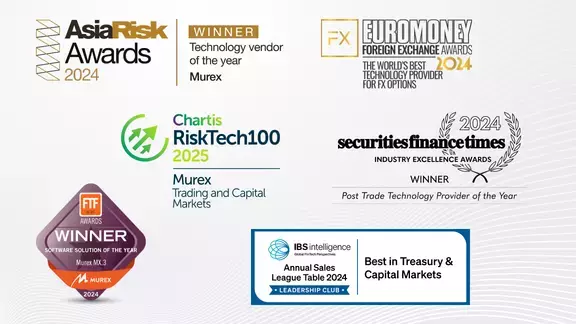
Our awards highlight a strong level of customer satisfaction and acknowledge our market expertise.
Visit our awards webpage- Careers
OCT
06Murex Wins Global Market Risk Provider, Derivatives Technology Provider of the Year at GlobalCapital Derivatives Awards
PARIS, October 6, 2026—Murex is pleased to announce dual wins at the GlobalCapital Derivatives Awards.
Murex was named Global Market Risk Provider of the Year and Derivatives Technology Provider of the Year.
The Derivatives Awards recognize leading banks, brokers, service providers, law firms, exchanges, and other key players for their contributions to the derivatives market. The awards focus on innovation, growth and work to improve the derivatives industry, as well as extraordinary effort on behalf of clients.
“As the derivatives landscape continues to evolve, MX.3 provides a resilient and scalable foundation for institutions looking to innovate, manage risk more effectively, and drive sustainable growth,” said Murex Head of Product Marketing Mickael De Oliveira Neves. “In periods of heightened market volatility, financial institutions need rapid product deployment and accurate, scalable tools to anticipate, monitor and explain market movements. Murex’s MX.3 platform delivers this through an integrated suite of advanced, enterprise‑wide risk management capabilities.”
Today, over 300 institutions—including 65 of the world’s Top 100 banks—rely on MX.3 to manage derivatives across asset classes. MX.3 covers all major workflows required to run a derivatives business. This unified approach reduces operational cost and gives institutions transparency and control to respond to evolving regulatory requirements and market conditions.
Murex’s MX.3 platform unifies trading, treasury, market risk, credit risk, collateral management, and XVA. Institutions strengthen risk governance, accelerate innovation, ensure regulatory compliance, and reduce operational and IT complexity through MX.3.
At the core of MX.3 is a comprehensive risk engine. Institutions maintain full control of pricing models, evaluation settings and computational resources, and experience clear governance across risk, finance, and reporting teams.
A single trade repository, shared models, and common data sets connect front office, risk, and operations, reducing reconciliation while preserving risk team independence for alternative models, market data and scenarios.
MX.3 continues to evolve as an elastic, digital risk platform. Cloud‑native grid computing, managed services, and ML‑accelerated analytics bring on‑demand scalability and rapid regulatory adoption. Open REST APIs further enable enterprise digitalization.
With regulatory requirements such as FRTB or climate scenarios, and AI‑driven analytics, MX.3 is already positioned to support institutions’ full risk agenda.
MX.3 supports the full life cycle of derivatives and structured products. It unifies pricing, real‑time analytics, trading, risk management and post‑trade processing within a single, consistent architecture. Institutions rely on MX.3 to accelerate time‑to‑market, reinforce governance, and operate efficiently across asset classes and regions.
The platform offers one of the industry’s most extensive product catalogs, with more than 2,400 financial instruments. Clients can rapidly introduce new products. REST APIs enable firms to integrate their proprietary quantitative libraries.
A significant area of innovation is Murex’s application of machine‑learning techniques to derivatives valuation. MX.3 embeds models trained to replicate pricing engines for complex instruments such as autocallables.
Latest news
see more28 Sep 2026
Banorte, Murex Lead Total Return Swaps Implementation in Mexico as Part of Broader Derivatives Transformation
Move is the latest advancement of a multi-year innovation strategy
see more23 Sep 2026
Murex and Google Cloud Announce Strategic Partnership to Accelerate Innovation in Capital Markets
Murex achieves MX.3 certification on Google Cloud, broadening client choice for cloud deployments
see more23 Jul 2026
Murex Recognized in Chartis STORM Rankings for Quantitative Analytics and Buy-Side Risk
Ranked fifth in Quantitative Analytics50 and eighth among technology vendors in BuySideRisk50
see more20 Jul 2026
MKS PAMP Goes Live on MX.3 with MXSaaS to Scale Precious Metals Derivatives Business
see more09 Jul 2026
Murex AI Research Launches to Shape, Explore Evolution of Artificial Intelligence in Capital Markets
see more17 Jun 2026
Murex is FTF News Technology Innovation Awards Service Provider of the Year and Provides Best Digital Asset Solution
see more12 Jun 2026
Murex Positioned First in IBSi Sales League Table for Eighth Consecutive Year
Strong global market position reaffirmed; MX.3 recognized in Islamic
Treasury and Capital Markets category againsee more18 May 2026
Murex Named Category Leader in Chartis RiskTech Quadrant for Enterprise Market Risk Solutions
see more08 Apr 2026
Leading German Bank Helaba Goes Live on MX.3 for Collateral Management Solution
Murex platform migration lays groundwork for implementation at Landesbank
see more02 Apr 2026
Murex MX.3 for E/CTRM Solution has Robust Showing Across Energy Risk Software Rankings
Driven by client and partner votes, field-leading 19 top positions recognize company’s powerful, evolving energy and commodities offerings
- Our clients