-
Our solutions
- Our clients
With 300 clients and 60,000 users spread across 60 countries around the world, Murex has a truly international client base of capital markets participants.
view all case studies- Who we are
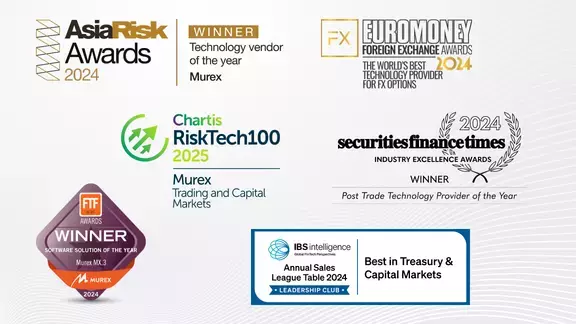
Our awards highlight a strong level of customer satisfaction and acknowledge our market expertise.
Visit our awards webpage- Careers

Improving Financial Risk Scenarios without Replacing the Model you Trust is Totally Possible
Deep MKV-TS adds a controlled, traceable volatility correction to an interpretable reference model, helping institutions capture how risk develops over time while preserving the model, controls and expertise already in place.
Financial institutions invest heavily in models that are fitted to their data, understood by their teams, reviewed through governance processes and embedded in risk systems. Those strengths should not be discarded lightly.
However, even a well-calibrated model can tell an incomplete risk story.
A model may describe the next market move accurately and also miss what happens across an entire path. Volatility can persist. An early drawdown can affect risk much later. Calm or turbulent regimes can last longer than expected. These effects can affect decisions that depend on the full distribution and sequence of outcomes, including limit setting, stress testing, capital allocation, hedging and position sizing.
One response is to replace the existing model with a flexible neural generator. Such models can learn complex patterns, but they also introduce a completely new mechanism to validate and might remove the explicit one-step dynamics that users can inspect. Replacement can also create practical questions around benchmark continuity, change approval, production integration and the ability to explain results to internal model committees and supervisors.
At Murex AI Research, we are exploring a pragmatic approach: preserving the interpretable reference model and adding a targeted correction for the path-dependent risk dynamics it does not capture well.
A correction layer, not a replacement
Deep MKV-TS enriches an interpretable reference model. The reference continues to provide the expected next price move and baseline conditional volatility. Its drift is preserved. Deep MKV-TS learns only how volatility should be adjusted as a scenario unfolds.The objectives are explicit. Users choose the properties that matter for the intended application, such as the distribution of realized volatility, volatility clustering, maximum drawdown, or the relationship between earlier market events and future risk. The neural component does not decide what a "good" scenario should reproduce. It learns the sequential correction required to meet those selected objectives.
Training follows an iterative cycle. The reference model generates scenarios. Their chosen risk features are compared with the data. Path-dependent optimal control then links the mismatch measured over a complete scenario to the earlier dates that contributed to it. A recurrent neural network learns how the corresponding volatility adjustment should depend only on the history available at each date.
A regularization penalty discourages unnecessary departures from the reference. This keeps the correction anchored to the original dynamics. It also creates a visible audit trail: For every scenario and time step, users can compare corrected volatility with reference volatility and see when risk was increased or reduced, by how much and for how long.
Validation from a known answer to unseen markets
The research tests the method in stages. First, a small GARCH scenario tree provides an answer that can be calculated exactly. With 729 possible paths, every future can be enumerated. Trained only from sampled continuations, Deep MKV-TS recovers 96.4 percent of the improvement achieved by the exact calculation. This verifies the learning chain before moving to larger problems.Synthetic experiments then isolate harder effects. On Heston data, where volatility is hidden from the model, the correction substantially reduces errors in realized-volatility distribution, persistence, early-to-future dependence and maximum drawdown. In an eight-regime Heston mixture, it improves every reported diagnostic despite starting from a pooled reference that averages the regimes together.
A delayed-volatility experiment tests long memory directly: An early drawdown raises volatility only after a lag. At the longest 512-step horizon, Deep MKV-TS removes 62.2 percent of the reference model's aggregate distributional error, improves temporal-dependence measures and completes all four training runs. The comparison based on direct optimization completes only two of four runs and worsens the dependence measures. The correction also remains traceable: Paths that cross the early drawdown threshold receive an earlier and stronger volatility adjustment.
Better conditional forecasts on held-out futures data
The real-data study uses one-second ES, NQ and YM equity-index futures with a chronological split: 496 sessions for training, 144 for validation and 123 unseen sessions for final testing.For each test session, the first 65 prices are observed. The method retrieves 256 generated histories that most closely resemble that opening from a bank of 8,192 scenarios, then uses their next 32 returns as the forecast distribution. In practical terms, the test asks whether the generator produces plausible continuations for the specific market history observed that day, rather than paths that look realistic only on average.
Forecasts are scored on cumulative return, individual returns and future realized volatility. Across the three indices and three targets, Deep MKV-TS improves on its reference model in all nine cases. It also records a lower error than the state-of-the-art neural benchmark in eight cases, a short-block historical bootstrap in all nine and a full-session bootstrap in eight.
From statistical improvement to usable risk capacity
The final experiment turns the scenarios into a drawdown-based position-sizing decision for ES. The objective is to choose exposure and to keep the estimated probability of a maximum drawdown above 1 percent below 10 percent.Deep MKV-TS supports average exposure of 1.99 times capital, compared with 1.85 for the reference, while the observed breach rate is 8.13 percent—below the prescribed 10 percent limit. In this experiment, better conditional scenarios translate into greater usable risk capacity and do not breach the chosen test-sample threshold.
This is not a trading backtest and does not claim universal dominance over every alternative. It tests whether the correction makes the reference scenarios more useful for a concrete risk decision.
A pragmatic path to richer scenario generation
For model users, the proposition is straightforward: Keep the established model as the transparent anchor, target the path-dependent risk properties it misses and inspect the correction along every generated path.The current evidence is strongest for continuous, single-asset intraday series. Jumps, overnight gaps and cross-asset dependence remain important extensions. Within that scope, Deep MKV-TS shows that the choice need not be between a transparent but incomplete model and a flexible generator built from scratch. The existing model stays in place, while a controlled correction helps it capture how risk changes over time.
In July, we announced the launch of Murex AI Research. As part of its commitment to the research community, Murex AI Research will continue to share its work through research papers, technical articles and accessible summaries. Revisit the first of these. Follow Murex on LinkedIn, where we’ll promote this work.
You might be interested in ...
- Our clients